

CFA® Level II formula sheet
Key formulas from EduFite's Level II lessons, grouped by topic. Free to read and search.
Studying for Level I? See the Level I formula sheet.
Get the full Formula Guide (PDF)
All 290 formulas on this page, explained: what each one tells you, when to use it, worked examples and the mistake to avoid. Free, with a short series of study emails, then one study note a month.
We use your email to send a short series of free study emails, then one study note a month, which may include offers for EduFite paid plans. Every email has an unsubscribe link. Privacy Policy.
290 formulas
Quantitative Methods
- R-squared: explained variation; : total variation
- Adjusted R-squared: observations; : independent variables
- Sum of squared errors
- Mean squared error: degrees of freedom for the error
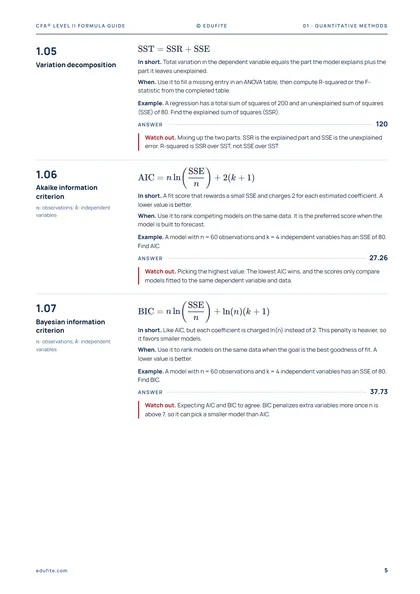
- Variation decomposition
- Akaike information criterion: observations; : independent variables
- Bayesian information criterion: observations; : independent variables
- t-statistic for a coefficient: hypothesized value; : standard error
- F-test for restricted model: number of restrictions; : unrestricted degrees of freedom
- F-statistic for overall fit: mean regression square; : mean squared error
- Regression prediction equation: estimated coefficients
- Breusch-Pagan test statistic: independent variables in the auxiliary regression
- Variance inflation factor: R-squared from regressing on the other X variables
- Leverage threshold: leverage of observation
- Studentized residual: standard error of the deleted-observation residual
- Cook's distance: residual; : leverage; : mean squared error
- Intercept dummy variable model: dummy (1 if in the group, else 0)
- Slope dummy variable model: interaction term; : extra slope for the group
- Logit log-odds model: probability of the event
- Probability from logit model
- Likelihood ratio test statistic: log-likelihood; degrees of freedom: number of restrictions
- Linear trend model: time index (1, 2, 3, and so on)
- Linear trend forecast: last observed period
- Log-linear trend model
- Implied growth rate per period
- First-order autoregressive model: the previous value of the series
- Autocorrelation t-statistic: number of observations in the series
- Mean-reverting level
- Two-period-ahead forecast: the one-period forecast, used as the input
- Root mean squared error
- Random walk without drift
- Random walk with drift: drift (expected change each period)
- First difference of a random walk
- Dickey-Fuller transformation: unit root
- n-period moving average
- Seasonal autoregressive model: value from the same quarter last year
- ARCH(1) regression significant: the errors show ARCH
- LASSO objective function: penalty weight
- Min-max normalization
- Standardization (z-score)
- Accuracy: true positives; : false positives; : true negatives; : false negatives
- Precision
- Recall (sensitivity)
Economics
- Cross rate and reciprocal quote: units of A per one unit of B
- Forward rate from forward pointspoints are quoted in units of 0.0001
- Forward premium or discount
- Covered interest rate parity: units of foreign currency per domestic; : rate for the horizon
- Uncovered interest rate parity: expected change in the exchange rate
- Relative purchasing power parity: inflation rate
- Absolute purchasing power parity, : price of the same basket in each country
- International Fisher effect: expected inflation rate
- Balance of payments identity
- Equity return decomposition: number of years; : earnings; : price to earnings ratio
- Cobb-Douglas production function: technology; : capital; : labor; : capital share
- Growth accounting equation: total factor productivity growth
- Steady-state growth per capita: TFP growth; : capital share of output
- Constant marginal product of capital: constant marginal product of capital
Financial Statement Analysis
- Equity method investment balance
- Equity method income: ownership share
- Excess purchase price
- NCI, full goodwill method: minority share of the subsidiary
- NCI, partial goodwill method: minority share of the subsidiary
- Diluted shares, treasury stock method
- Pension funded status
- Cumulative translation adjustment
- Organic sales growth
- Liquidity coverage ratio
- Net stable funding ratio
- Combined ratio
- Loss and LAE ratio
- Underwriting expense ratio
- Insurer duration gap
- Earnings persistence regression: intercept; : error term
- Altman Z-score: net working capital; : total assets; : market equity
- Five-factor DuPont ROE
- Three-factor DuPont ROE
- Adjusted net income (ex associates)
- Adjusted assets (ex associates)
- Adjusted asset turnover
- Capital allocation ratio
- Net operating assets
- Aggregate accruals, balance sheet method
- Balance sheet accruals ratio
- Aggregate accruals, cash flow method
- Cash flow accruals ratio
- OCF before interest and taxes
- Operating cash flow to operating income
- Cash return on assets
- Pro-rata value of subsidiary
- Implied value of parent ex-subsidiary
- Implied P/E ex-subsidiary
- Discount to benchmark P/E
Corporate Finance
- Effective dividend tax, double taxation: corporate tax rate; : personal dividend tax rate
- Effective dividend tax, split-rate: corporate rate on distributed earnings
- Target payout dividend adjustmentAdjustment factor: 1 divided by years to reach target
- Free cash flow to equity: fixed capital investment
- Weighted average cost of capital: market-value weights; : marginal tax rate
- Cost of preferred stock: preferred dividend; : market price
- Emerging-market cost of debt: country risk premium
- Bond price and yield to maturity: coupon; : face value; : periods
- Historical equity risk premium
- Gordon growth equity risk premium: index dividend yield; : long-run growth
- Macroeconomic model equity risk premium: inflation; : real earnings growth; : net buyback boost
- Gordon growth cost of equity: next dividend; : current price; : growth rate
- Bond yield plus risk premium: equity premium over the firm's own bond yield
- CAPM expected return
- Fama-French three-factor model: size premium; : value premium
- Fama-French five-factor model: profitability premium; : investment premium
- Expanded CAPM, private company: size premium; : specific-company risk premium
- Build-up cost of equity: size premium; : specific-company risk premium
- Global CAPM
- Country risk premiumSpread: EM sovereign yield in developed currency minus developed yield
- Emerging-market equity risk premium: exposure to country risk (0 none, 1 full)
- Takeover premium
Equities
- Mispricing versus valuation error: your estimate; : true value; : market price
- Dividend discount model: dividend in year ; : required return on equity
- Gordon growth model: next year's dividend; : required return; : growth
- Market-implied growth rate: expected dividend yield
- Market-implied required return: dividend yield; : capital gains yield
- Value with growth opportunities: next year's earnings; : required return
- Justified leading P/E: retention rate; : required return; : growth
- Two-stage dividend model: years in stage 1; : terminal value at year
- H-model: half the transition period in years
- Sustainable growth rate: earnings retention ratio
- PRAT growth decomposition: margin; : retention; : asset turnover; : leverage
- Terminal value, constant growth: value at year ; : long-run growth
- Terminal value from P/E: expected P/E at year
- Equity value from firm value
- FCFF from net income: non-cash charges; : fixed capital investment; : working capital investment
- FCFF from operating cash flow: fixed capital investment
- FCFF from EBIT: depreciation; : working capital investment
- FCFF from EBITDA: depreciation; : working capital investment
- FCFE from FCFFnet borrowing: new debt less repayments
- FCFE from net income
- FCFE with constant debt ratio: debt share of net investment
- FCFF constant growth model: constant growth rate of FCFF
- FCFE constant growth model: constant growth rate of FCFE
- Two-stage FCFF valuation: terminal value at year
- Terminal value from FCFF: long-run growth rate
- Terminal value from EV/EBITDA
- Firm value with non-operating assets
- Trailing P/E: current price
- Forward P/E: current price
- PEG ratiogrowth in percentage points, such as 12
- Price to book value: common equity per share
- Price to sales
- Price to cash flow
- Dividend yield
- Enterprise value
- EV/EBITDA
- EV/Sales
- Harmonic mean P/E: weight of stock
- Residual income: EPS; : beginning book value per share
- Residual income valuation model: current book value per share
- Justified P/B from residual income
- Single-stage residual income value: constant growth rate of RI
- Clean surplus relation: earnings; : dividends
- Multistage residual income model: first year of continuing RI
- Continuing residual income value: persistence factor, 0 to 1; : last forecast year
- Residual income with comprehensive income
- Tobin's q
- Total discount from DLOC and DLOM: lack of control; : lack of marketability
- Capitalized cash flow method: sustainable growth rate
- Unlevered beta: tax rate; : debt to equity
- Relevered beta: target debt to equity of the private firm
Fixed Income
- Forward rate model: forward rate for years, starting in
- Spot rate from forwards
- Discount factor: spot rate for maturity
- Z-spread: constant spread added to every spot rate
- Portfolio effective duration: market value weight; : effective duration of bond
- Arbitrage-free bond value: spot rate for year ; : face value
- Up rate from down rate: annual rate volatility; and : higher and lower rate
- Two-period tree rates: up, up; : up, down; : down, down
- Binomial node value: next-period up and down values; : coupon; : node rate
- Pathwise valuation
- Call option value
- Put option value
- Option-adjusted spread
- Effective duration: price if yield falls ; : price if yield rises
- Effective convexity
- Capped floater value
- Floored floater value
- Convertible conversion valueConversion ratio: shares received per bond
- Convertible minimum value
- Non-callable convertible value
- Callable convertible value
- Loss given default
- Expected loss: probability of default
- Credit valuation adjustment
- Fair value of risky bond: value assuming no default
- Credit spread price impact
- Equity payoff as a call: asset value at ; : face value of debt
- Debt payoff at maturity
- CDS upfront premium
- CDS cash settlement payout
- CDS spread approximation
- Survival probability: number of years
- Default probability in year t: probability of surviving to the start of year
- CDS upfront payment
- CDS profit from spread change
- CDS basis
Derivatives and Risk Management
- Long forward value at expiry: spot price at expiry; : forward price
- Short forward value at expiry: spot price at expiry; : forward price
- Carry arbitrage forward price: PV of carry costs; : PV of carry benefits
- Forward price, continuous compounding: continuously compounded risk-free rate
- Forward value during life, no carry: spot price at time
- Equity forward price: present value of dividends before delivery
- FRA fixed rate: time to FRA start; : FRA period; : year fractions
- FRA settlement amount: notional; : LIBOR at ; : discount rate
- Bond forward price: PV of coupons paid during contract; : accrued interest
- Quoted bond futures price: conversion factor; : accrued interest at delivery
- Swap fixed rate: accrual period; : discount factor for date
- Receive-fixed swap value: fixed leg value; : floating leg value
- Currency swap value: price of currency b in currency a; : fixed bond values
- Currency swap fixed rate: par value per unit of notional, currency a
- Equity swap equity leg: equity notional; : equity return in period
- Equity swap fixed leg: fixed-leg accrual period
- Binomial hedge ratio: option values; : stock prices
- Binomial call price, hedge method: down-state stock price; : down-state call value
- Risk-neutral up probability: up and down factors; : growth factor
- Binomial call price, expectations method: risk-neutral probability of an up move
- Put-call parity: put value; : strike; same strike and expiry
- American option node value
- Put exercise value: strike; : stock price at the node
- Escrow-adjusted stock price: stock price used to build the tree
- BSM call price: continuous carry benefit rate; : normal CDF
- BSM put price: equals 1 minus
- Black model call on futures: futures price in place of spot
- Delta hedge size: delta of the hedging instrument
- Delta-gamma price change: option delta; : option gamma
Alternative Investments
- Theory of storage: futures price; : spot price
- Commodity futures total return
- Spot return: spot price at start and end
- Roll return: expiring contract price; : next contract price
- Net operating income: effective gross income
- Debt service coverage: a typical lender minimum, not a fixed rule
- Direct capitalization value: next-year net operating income
- Cost approach value
- Funds from operations
- Adjusted funds from operations
- Pro forma cash NOI
- Expected NOI: expected NOI growth rate
- Operating property value
- Gross asset value: accounts receivable
- Net asset value
- NAV per share
- Price to FFO
- Price to AFFO
- Enterprise value to EBITDA
- Net exposure
- Sharpe ratio
- Sortino ratio: minimum acceptable return
- Stress-regime factor model: 1 in stress, else 0; : extra beta in stress
Portfolio Construction
- Present value model: real rate; : inflation; : inflation risk; : asset risk
- Real rate from IRS: marginal utility ratio, future to today
- Value with covariance adjustment: marginal utility ratio; : next-period price
- Taylor rule: natural real rate; : target inflation; : output gap
- Break-even inflationIncludes a premium for inflation uncertainty
- Bond risk premium
- Expected credit loss
- Price-to-earnings ratio
- Risk-adjusted alpha: portfolio beta to the benchmark
- Active return decomposition: active weight; : sector active return
- Sharpe ratio: standard deviation of portfolio returns
- Information ratio: tracking error
- Squared Sharpe ratio sum: benchmark Sharpe ratio
- Optimal active risk: benchmark volatility
- Expected active return: skill; : independent bets per year
- Fundamental law of active management: skill; : independent bets per year
- Effective breadth: number of assets; : average correlation of active returns
- Constrained information ratio: transfer coefficient
- Information coefficient from hit rate
- Active return: benchmark return
- Alpha forecast from skill and score: standardized forecast score
- Constrained expected active return: transfer coefficient
- Realized active risk: risk from uncertain skill
- CAPM expected return: sensitivity to the market
- APT expected return: factor risk premium; : factor sensitivity
- Multifactor return model: factor realization; : asset-specific error
- Carhart four-factor model: market; : size; : value; : momentum
- Macroeconomic factor modelFactors are surprises; is the expected return
- Standardized factor sensitivity
- Active return from factor tilts: factor return; : security selection
- Tracking error: sample standard deviation
- Active risk decomposition
- Parametric VaR, 5%: portfolio return standard deviation
- Parametric VaR, 1%: portfolio return standard deviation
- Annual to daily return and risk250 trading days per year
- Incremental VaR
- Duration price approximation: Macaulay duration; : yield per period; : yield change
Get the full Formula Guide (PDF)
All 290 formulas on this page, explained: what each one tells you, when to use it, worked examples and the mistake to avoid. Free, with a short series of study emails, then one study note a month.
We use your email to send a short series of free study emails, then one study note a month, which may include offers for EduFite paid plans. Every email has an unsubscribe link. Privacy Policy.
Your next step
Put the formulas to work
The exam gives you no formula sheet, so formulas stick best when you use them on item sets. Quantitative Methods is free to study in full on EduFite for Level II: its lessons and practice questions, with a free account and no card.
Study Quantitative Methods freeOr test yourself first with the free Level II flashcards.